Think You Can't Claim the Home Office Because You Live in a Studio? Benefits of a 3-Square-Foot Home Office
When most people think about claiming a home-office tax deduction, they picture an entire bedroom converted into an office, complete with a desk, computer, and office chair.
But what if you live in a studio apartment? Or what if you already rent commercial office space for your business?
Here's something that might surprise you: the IRS doesn't require an entire room to qualify for a home-office deduction.
Under certain circumstances, a workspace as small as three square feet could potentially qualify.
Even more interesting, the biggest tax savings might not come from deducting your rent or utilities. They could come from deducting business mileage that would otherwise be considered nondeductible commuting.
Let's break down how this works.
Does the IRS Require a Separate Room for a Home Office?
No. The IRS does not require an entire room to qualify for a home-office deduction.
Under Internal Revenue Code Section 280A, taxpayers may qualify for a deduction when a portion of their residence is used regularly and exclusively for qualifying business purposes.
Key Point
The biggest financial benefit of a small home office may not be the deduction for housing expenses. A qualifying home office that serves as your principal place of business may allow you to deduct transportation expenses that would otherwise be treated as commuting.
The IRS specifically recognizes that a home office can consist of a separately identifiable area within a room. Permanent walls or partitions are not required.
For example, you could potentially designate a small section of your bedroom, living room, or another area of your home for business use.
However, the space must satisfy the applicable requirements. Simply placing a laptop somewhere in your apartment isn't enough.
Does the IRS Require a Separate Room for a Home Office?
Imagine purchasing a filing cabinet that measures 18 inches wide and 24 inches deep.
That filing cabinet occupies exactly three square feet of floor space.
Now imagine using that filing cabinet exclusively to store business records, client documents, and business supplies.
You regularly perform your business's administrative activities at home, using the designated space for work.
Under the right circumstances, a small workspace like this could potentially support a home-office deduction.
The important distinction is that the IRS cares about how the space is used, not simply how large it is.
A filing cabinet by itself does not automatically qualify as a principal place of business. The actual arrangement and business activities must satisfy the applicable legal requirements.
Key Point
The IRS does not impose a minimum square footage requirement for a home office. However, the space must satisfy the regular-use, exclusive-use, and other applicable business-use requirements. A filing cabinet alone does not automatically establish a qualifying home office.
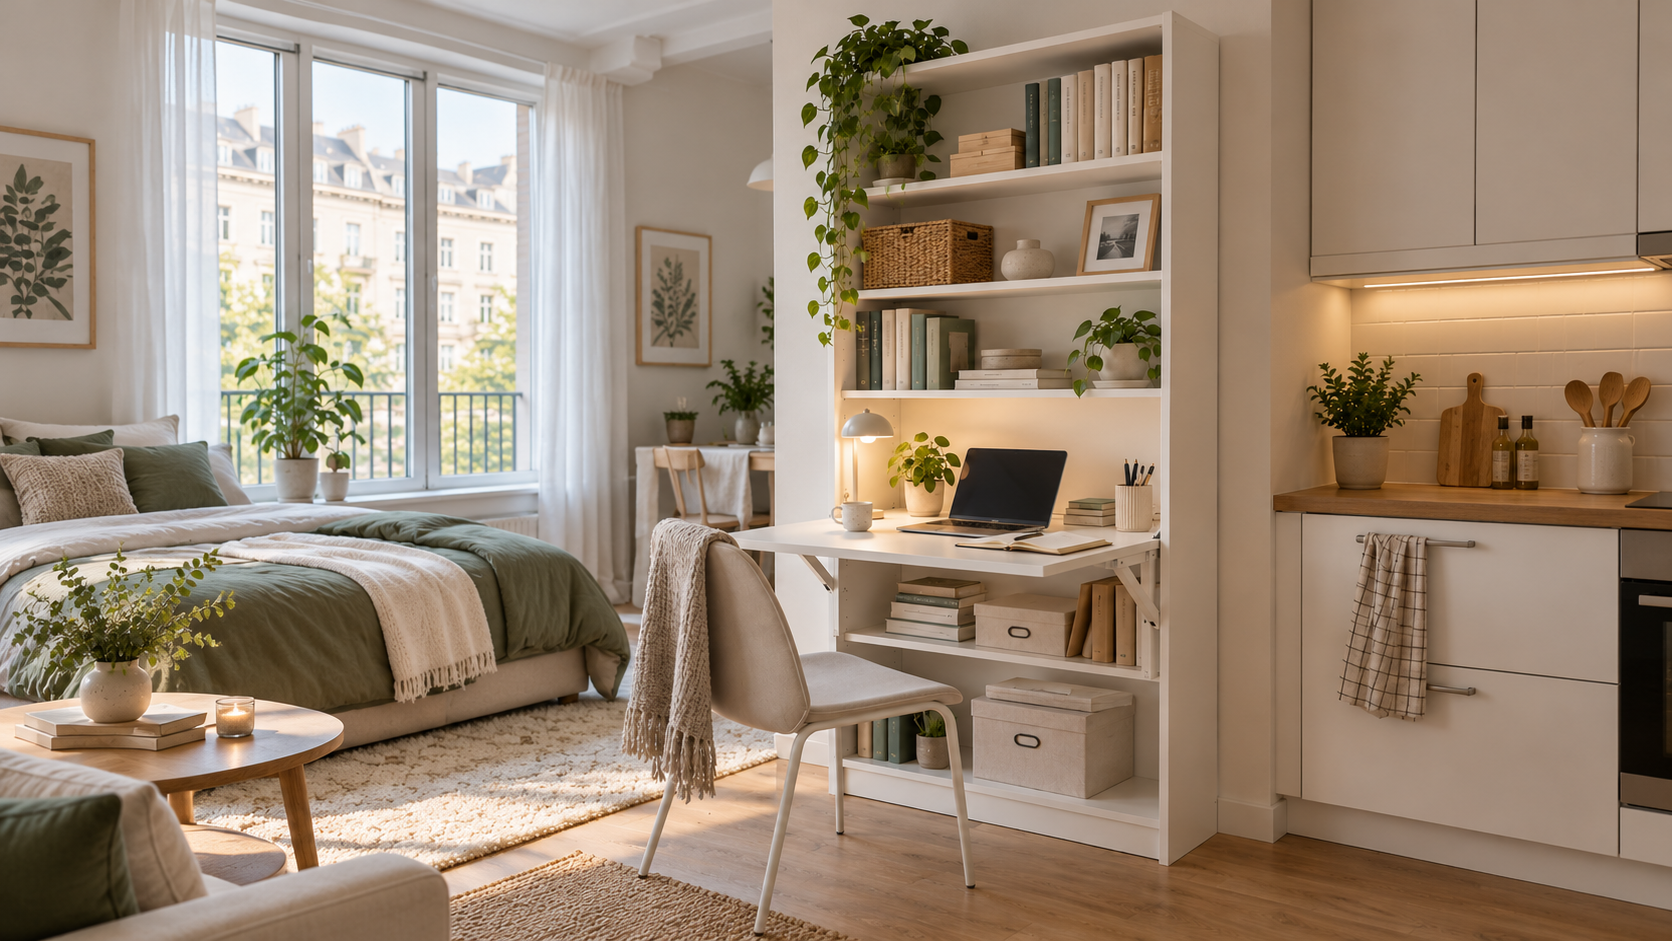
Live in a Small Studio? Your Furniture Could Double as a Home Office
Living in a studio apartment doesn't necessarily mean giving up the home-office deduction.
For example, IKEA offers a BILLY bookcase with a foldable table.
The table folds away when it isn't needed, making it a practical option for someone living in a small apartment.
Imagine using the bookcase exclusively to store business records, reference materials, and office supplies while using the foldable table for administrative work.
If the workspace satisfies the IRS requirements for regular and exclusive business use, some of the area may qualify.
However, there's an important distinction.
If you also use that same table to eat dinner, watch television, or perform other personal activities, the table area generally wouldn't satisfy the exclusive-use requirement.
The same is true if you regularly store personal items alongside business supplies in the designated space.
The key isn't how much space you have. It's how you use that space.
The Real Tax Benefit: Turning Commuting Miles Into Business Mileage
Here's where things get interesting.
Most people focus on deducting a percentage of their housing expenses when discussing home-office deductions.
But a three-square-foot office probably won't generate a significant deduction for rent, utilities, or other household expenses.
The potentially larger benefit involves business mileage.
Generally, driving from your home to your regular workplace is considered commuting, which is not tax-deductible.
However, under Revenue Ruling 99-7, when your home qualifies as your principal place of business, travel between your home and another work location in the same trade or business may qualify as deductible business transportation.
Example: How a Business Owner Could Deduct More Than $5,500 in Mileage
Assume you own a small business and rent an office 15 miles from your home.
You travel to that office five days per week for 50 weeks.
Without a qualifying home office, those trips would generally be considered commuting.
Now assume you establish a qualifying home office where you regularly conduct your business's administrative and management activities.
Your home qualifies as your principal place of business, and your trips to the separate office qualify as business transportation.
Let's look at the potential deduction.
For 2026, the standard business mileage rate is 72.5 cents per mile from January through June and 76 cents per mile from July through December.
Using 7,500 qualifying annual business miles split evenly between the two periods, the potential mileage deduction would be $5,568.75.
What Makes Your Home a Principal Place of Business?
This is arguably the most important requirement.
Simply having a filing cabinet at home does not automatically make your residence your principal place of business.
Under IRC Section 280A(c)(1), your home can qualify as your principal place of business if:
You use the space exclusively and regularly for administrative or management activities of your business.
You have no other fixed location where you conduct substantial administrative or management activities of that business.
Administrative and Management Activities That Qualify
Examples include:
Preparing invoices and billing customers
Maintaining bookkeeping and financial records
Scheduling appointments
Ordering business supplies
Preparing business reports
Managing business operations
Can You Have Both a Home Office and a Commercial Office?
Yes. Having a separate commercial office doesn't automatically prevent your home from qualifying as your principal place of business.
Imagine a self-employed attorney who rents an office to meet clients but performs substantially all administrative and management work from a qualifying home office.
The attorney's home could potentially qualify as the principal place of business even though clients are primarily served elsewhere.
The important question is where the taxpayer actually performs substantial administrative and management activities.
Understanding the IRS Exclusive-Use Requirement
The IRS generally requires the designated home-office area to be used exclusively for business.
This means your workspace cannot routinely double as a personal-use area.
For example:
A filing cabinet containing only business records may support exclusive use.
A filing cabinet containing both personal and business documents may create problems.
A dining room table used for both family meals and business activities generally would not qualify as an exclusively used business area.
What Tax Court Cases Tell Us About Small Home Offices
There is some interesting Tax Court precedent involving small home offices and incidental personal use.
In Mills v. Commissioner, T.C. Memo 1991-592, the Tax Court addressed a home-office deduction involving a taxpayer who lived in a 422-square-foot apartment.
In Hughes v. Commissioner, T.C. Memo 1981-140, the Tax Court allowed a home-office arrangement involving a walk-through closet, despite the taxpayer passing through the area for personal reasons.
However, these cases should not be interpreted as blanket permission to use your home office for personal activities.
The facts matter, and the exclusive-use requirement remains important.
Who Can Benefit From the Three-Square-Foot Home Office Strategy?
This strategy may be especially useful for self-employed individuals and business owners who work at multiple locations.
Examples include real estate agents, attorneys, consultants, independent contractors, and other small-business owners.
Sole Proprietors and Independent Contractors
Qualifying sole proprietors may deduct home-office expenses on Schedule C, generally using Form 8829 or the simplified method.
S Corporation Owners and Accountable Plans
S corporation owners have different considerations.
An S corporation may be able to reimburse qualifying employee-shareholder home-office expenses through a properly structured accountable plan.
However, the reimbursement must meet the applicable accountable plan requirements and be properly substantiated.
What About W-2 Employees?
Most ordinary W-2 employees cannot claim a federal deduction for unreimbursed home-office expenses under current law.
Certain limited exceptions exist for specific employee business expenses, but the general home-office deduction is not available to most employees.
Documentation: How to Support Your Home Office Deduction
Before claiming a home-office deduction, business owners should maintain documentation demonstrating that the space satisfies the applicable requirements.
Helpful records include:
Measurements of the designated workspace
Photographs of the business-use area
Documentation of administrative activities performed at home
Records demonstrating regular and exclusive business use
Mileage logs showing business destinations, dates, distances, and business purposes
A qualifying home office should reflect how you actually operate your business, not merely a space created on paper to generate a deduction.
Final Thoughts: Small Space, Potentially Big Tax Savings
Tax planning isn't always about making major purchases or implementing complicated strategies.
Sometimes it's about understanding how existing tax rules apply to the way you already operate your business.
A home office doesn't necessarily require a dedicated bedroom, expensive furniture, or hundreds of square feet.
Under the right circumstances, even a small workspace may qualify.
And while the direct home-office deduction might be modest, the potential business mileage deduction could be substantial.
The key is ensuring your arrangement satisfies the IRS requirements and that your business activities support the treatment.
Are You Missing Valuable Business Tax Deductions?
At Sharp Tax & Accounting, we help small-business owners identify practical tax-planning opportunities and understand the rules behind legitimate deductions.
If you're self-employed and wondering whether your home office or business mileage qualifies for a deduction, let's discuss your situation.
Learn more about our Tax Preparation & Planning Services.
Dedicated to Being Sharp.
Sources and Additional Reading
Mills v. Commissioner, T.C. Memo 1991-592
Hughes v. Commissioner, T.C. Memo 1981-140
Disclaimer: This article provides general tax information and does not constitute individualized tax or legal advice. Eligibility for deductions depends on the taxpayer's specific facts and circumstances.